Skip to content

LIFT LENDING – MORTGAGE BROKERS
01

About us

Lift Lending provides access to the latest and most comprehensive list of products and services to best meet your financial needs. We specialise and are passionate about helping clients achieve their financial goals whether it be for first home buyers, financing or investment. This means taking the time to understand your short and long term goals with your life aspirations to negotiate the right finance options for your needs from the hundreds that are available. We will support you throughout the process and will work with you long after your loan has settled to make sure you are still getting the best value and most suitable loan for your ever changing lifestyle and goals. We have access to platforms and expertise from various groups including Mortgage Australia Group, AFG and our extensive list of industry specialists. If you want to become mortgage free faster and easier and to discuss or review your loan requirements call on the details below. Start saving today!

02

How we can help you?

Via our access to a diverse and comprehensive list of products and services

Working out your needs and requirements should not be rocket science How many times has the thought of trying to get a better structure to your financial requirements seem too overburdening? People often tend to leave this or put it in the ‘too hard basket’.  Whether you are new to the market, trying to simplify or find a better product or rate, we can provide the assistance that better meets the needs of your portfolio. We can provide access to assistance in determining your serviceability and portfolio needs through our extensive brokerage platform we use. By entering in your specific needs into the tools, we can help narrow down the products and rates that best suit your needs. The platforms we use help minimise the amount of rework when applying for different products through different institutions, saving you time.

Do you have a low deposit?

Have you got only a low deposit or are new to the market? – We can help.

Need to work out your overall loan size and see what is available?

How much can you borrow against your assets and find the best product for your needs. – We can help.

Not sure if you can service a new loan?

Not sure if your income can allow you to service the loan for your needs, whether it is a new house or your portfolio of loans? – We can help.

Meet your needs

We strive to find the products and services that best meet your needs – always.

03

Our Team
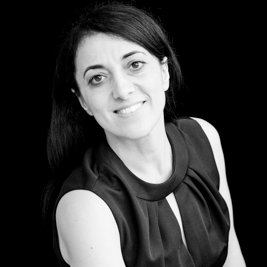
Sandra

Specialist Mortgage Broker / Partner
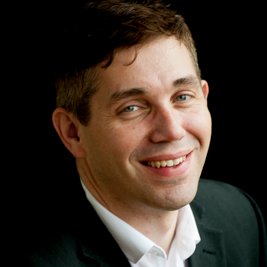
Peter

Partner

04

Testimonials

Posted on Google Google
Nathan King profile picture
Nathan King
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Sandra from Lift Lending was amazing and a joy to work with. As a first home buyer, I initially felt completely lost, but Sandra made everything simple, explained all my options, and helped me get a great rate and secure my ideal property. She has a broad range of lenders to choose from and went above and beyond to get professional exemptions that made a real difference. Super friendly and supportive — highly recommend!
Posted on Google Google
F C profile picture
F C
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
As an inexperienced home buyer in today's world, Sandra Oeding-Erdel from Lift Lending was the perfect choice for me. Sandra's extensive knowledge and advice in available products quickly provided me relevant options to perfectly suit my needs. Sandra simplified the process by guiding me through each step with clear, consistent, and concise communication. Sandra went above and beyond as my mortgage broker, her accessibility and efficiency second to none regarding the progression of my loan application approval. I highly recommend Sandra Oeding-Erdel from Lift Lending!
Posted on Google Google
Kyah Murphy profile picture
Kyah Murphy
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
I can’t recommend Sandra Oeding-Erdel from Lift Lending highly enough! As a first home buyer, I had so many questions and didn’t know where to start. Sandra made the whole process simple and stress-free — she explained all my options clearly, gave me a great range of lenders to choose from, and helped me secure a low interest rate with a product perfectly suited to my needs. Her extensive lender panel meant she was also able to access professional exemptions that really made a difference. I’m so grateful for her guidance and support — I wouldn’t hesitate to recommend Sandra at Lift Lending to anyone looking for a knowledgeable and genuinely caring mortgage broker!
Posted on Google Google
Daniel Jones profile picture
Daniel Jones
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
**Highly Recommend** Sandra and Peter were absolutely instrumental in helping me land a first home! I strongly recommend their service as a one stop shop for your lending and mortgage needs. I found Sandra and Peter to be informative, personable, and supportive through the application and approval process. If you value clear and consistent communication while traversing through the mortgage application process, I strong recommend Sandra and Peter!
Posted on Google Google
Nancy Ghobrial profile picture
Nancy Ghobrial
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
Even though I was outside of "standard" bank criteria, Sandra had this amazing tenacity and will, going above and beyond to find a great lending package at very competitive rates. She was incredibly thorough in preempting what information the banks would need which resulted in a relatively quick conditional approval and approval process. Sandra was always very responsive and took the time to answer all my many questions both over the phone and via email. I would have no hesitation in recommending Sandra.
Posted on Google Google
Brent Oeding-Erdel profile picture
Brent Oeding-Erdel
Google star 1Google star 2Google star 3Google star 4Google star 5Trustindex verifies that the original source of the review is Google.
These guys were amazing in the help. Didn’t know where to start or how to get into the mortgage process, and they helped us beyond belief ! Before we knew it we were able to be buying a house! Really professional, easy to talk to and super helpful! Stoked !

05

Latest News

News from our social media feed
Cover for Sandra & Peter Erdel - Lift Lending Peakhurst
Page likes: 39

Sandra & Peter Erdel - Lift Lending Peakhurst

(opens in a new tab)

www.liftlending.com.au Provides mortgage and lending product support to meet personal and investme
Pop Quiz - Can you identify these loans? Save time and money by knowing the difference.The home loan market is overflowing with catch-phrases and complicated jargon. But if you only have room left in your brain for one more lesson - make sure you know the difference between the different types of loans available. This could save you time and money in the long run.Variable Rate LoanVariable rate loans generally have a low interest rate and allow you to select some additional features. These loans are popular with borrowers because they allow you to pay the going rate, which goes up and down depending on the official cash rate set by the Reserve Bank. There are also 'basic variable rate' loans available, offering a lower interest rate but usually without any additional features.Introductory Rate LoanAn introductory Rate loan gives you a discount on the standard variable rate for a set period of time. This can be a great way to ease yourself into the role of mortgage-holder, but it's important to compare the rate that the lender will charge you when the honeymoon period is over.Fixed RateFixed rate loans offer a guaranteed interest rate for a period of time - usually 1 to 5 years. This can be an excellent safeguard if you're on a tight budget and worried about interest rates rising. Keep in mind, though, the interest rate will be higher than a variable rate.Construction LoanConstruction loans allow you to borrow in stages, depending on how much work has been done to construct your home. Rather than making repayments on the entire amount and also having to rent while you build, this loan allows you to borrow what you need to pay the builder as they reach specific milestones.Low / No deposit loansThese loans allow you to get into the property market even if you don't have enough saved for a sizeable deposit. It's important to keep in mind that you will still need to pay some costs involved with the transaction, such as stamp duty, conveyancing costs and moving costs. And if you haven't been able to save anything towards a deposit, try to be honest with yourself about whether you can realistically afford to pay off a mortgage right now.Low-docDesigned for self-employed people, low-doc loans allow you to borrow without using the same methods to prove your income. Often these loans have a higher interest rate, and generally you can't borrow more than 80% of the property value.Credit Impaired / Non-ConformingNon-conforming loans allow people to get back into the game even if their credit history is not great, or they don't meet lender's criteria for other reasons. These loans come with high interest rates due to the risk involved for the lender.Line of CreditA line of credit is like having a big overdraft on your mortgage. You can use this feature to save a lot of money on interest, because if you deposit everything into your loan you can access the funds whenever you need them, as well as any equity you have acquired. This option is best suited to people who have good financial habits, and can avoid the temptation to go on a wild spending spree.Equity ReleaseAlso known as a reverse-mortgage, equity release loans allow you to borrow some of the equity in your home while you still live there. This option is popular with retirees, but it's important to make sure that the lender wont' allow you to chew up all of the equity in your home. Ask about a 'no negative equity guarantee'. ...
View on Facebook (opens in a new tab)
Home burglaries are a fact of life. Every year more than 20,000 homes in Australia are broken into - the majority during the day time when people are at work. That's the bad news.The good news is that there are plenty of simple, low-cost steps you can take to greatly reduce your chance of getting burgled. Remember, it's all about making your home a harder target to break into than other people's. Most burglars enter via a garage door, back door, kitchen or bedroom window. Burglar-proof these and you'll significantly improve your chances of never suffering from a break-in. 1. Door locksHave key-operated two-cylinder deadlocks fitted to all external hinged doors. A quality knob-inlock set will have a 'dead latch' mechanism to stop burglars using a credit card to open it.While looking at external doors, you may also want to check that they are solid and robust. If not, perhaps you should replace them, or add a security screen. You may also want to consider fitting a wide angle peephole on your front door. 2. Sliding doorsA favourite point of entry for burglars! Fit key operated locks or patio bolts to all external sliding doors, such as patio/veranda doors.Sliding doors can also be made more secure by inserting a wood or metal dowel into the track to limit movement. 3. WindowsAn open window, visible from the street, may be the only reason that your home is chosen by a burglar. Ground floor windows are more susceptible for obvious reasons.Make sure you have a security grill, security screen or burglar bars applied to all accessible windows, or alternatively have key-operated single cylinder window locks fitted. 4. Warning stickersPlace highly visible stickers on or near front doors and windows, which indicate an alarm system, dog or membership of neighbourhood watch. Your local police station should have an anti-crime adviser who can help provide these. 5. Light timersInstall light timers to switch on automatically if you aren't home when it gets dark, or have gone away for a few days. The timers should mimic when you would usually switch lights on or off. They are not expensive and are available at most hardware stores. 6. Exterior lightingExterior lighting is also a good deterrent, provided it is switched on and off as though someone is at home. Make sure the approach to your house, especially any entryway, is brightly lit, controlled by a light timer if necessary - this also makes it safer and more comfortable if you come home after dark. 7. Motion sensor lightsThese are useful to install, especially at the back of a house or apartment. Infra-red motion sensor lights are also easily available and not very expensive. An unexpected light going on is a definite deterrent to a burglar who will wonder what other security devices you have in place. 8. Alarm systemsBurglar alarms definitely increase the potential and fear of being caught by the police.There are a wide variety of alarms available - you need to make sure that the one you choose has visible signage and is properly programmed, installed and maintained.Some alarms are routed to a police station or alarm control centre. If yours relies on neighbourhood response, make sure your neighbours are able and willing to respond. 9. Home safesBurglars know all the hidey holes to look for keys, valuables and important documents. The price of a good home safe is falling, so setting one up could be a good investment. Home safes need to be anchored into the floor or permanent shelving, and should not be kept in the master bedroom or cupboard. Use the safe regularly, so it becomes routine and keep the code secret. 10. Protect your IDIt's a good idea to take photographs around your house of all your valuables - important proof for an insurance claim if you ever need to make one. This can be kept in a safety deposit box, safe, or with a relative. Receipts for bigger ticket items are also useful to keep for the same reason.Consider taking photocopies of your passport, driver's license and all the cards in your wallet and store these in a safe place. ...
View on Facebook (opens in a new tab)
How many ways can you buy a swimming pool?Question: How many ways can you buy a swimming pool?Answer: At least 8 different ways that I can think of.And not all of those ways may be suitable for everyone - here is my list.Not everyone wants a swimming pool either. But perhaps a new car, maybe a boat, a motorbike or a decent holiday? A caravan or a new garage? An aeroplane even?Doesn't really matter what it is, but if you need to spend a serious amount of money, it may be worth looking at some of the things you can do with your home loan to facilitate your new purchase. You see, 6 of those 8 different ways I mentioned actually involve your home loan, so it's probably worth a look first, just to make sure.That's where I can help. It doesn't cost anything to check out what would work for you, and then you can actually make an informed choice.The least I can do is point you in the right direction and the privacy act ensures our conversation is entirely confidential.What do you think?Contact me and we'll see where you stand. www.mortgageaustralia.com.au/email/files/8waystobuythatpool.pdf ...
View on Facebook (opens in a new tab)
Don't kick yourself later - ask these questions today and avoid loan confusion.There's nothing worse than walking out of an important meeting, only to realise that you forgot to ask some important questions. One of the most important meetings you will have when you enter the property market is your initial meeting with a mortgage broker.In order to get the most value out of your appointment, and improve your chances of being approved for a loan, you need to come along prepared to answer a host of questions about your finances and your living situation.But don't forget to ask some questions of your own. After all, the goal is to find the right loan for you, which won't happen if you don't speak up. When meeting with your mortgage broker, remember to ask:Which loan is right for my situation? There are a range of loans available but your mortgage broker should be able to help you decide which ones best fit your lifestyle.What is my borrowing power? This is usually based on your income and financial commitments, and it can vary greatly from one lender to another.What percentage of the property can I borrow? It's important to know how much you need to put down as a deposit, and also whether you need to pay other upfront costs, or whether they can be included in the loan amount.Will I have to take out LMI? Lenders Mortgage Insurance covers the lender in case you become unable to make your repayments, and there is a shortfall when the property is sold. Some lenders require borrowers to pay this amount upfront.Which loan offers the best rate? Some loans might offer a good introductory rate, but it's important to look at the ongoing rate once the honeymoon period is over.What flexibility does the loan offer? Can I make changes down the track? What if I want to make a lump sum payment in the future?Is the rate fixed or variable? Variable rates are usually lower, but keep in mind that they can change frequently. Fixed rates are a little higher but they provide some certainty for those on a strict budget. However fixed rate loans are usually a lot less flexible than variable rate loans.What will my repayments be? It's important to look at your budget and make sure you're not over-committing yourself.How much is the loan establishment fee? This is another cost that is often payable upfront, so you will need to ensure that you have funds available at settlement if this is the case.Are there any ongoing fees associated with the loan? Monthly account keeping fees can vary between lenders so it's important to make sure you compare your options.Are there any conditions to be aware of such as discharge costs, fees to change the loan? Not asking this question could be very costly if you're planning to refinance down the track, or make a significant lump sum payment in a few months. ...
View on Facebook (opens in a new tab)
What you need to know about the most important part of your home loan:Are you an expert on all lending related topics? That's okay - most people aren't. If you're still trying to understand the truth about interest rates, you're not alone. Here are a few answers to the questions you were too embarrassed to ask.How are interest rates determined?The Reserve Bank of Australia (RBA) sets the official interest rate or 'cash rate' which takes into account a whole list of factors about how the economy is performing at that point in time. The RBA meets once a month to review the inflation rate, unemployment figures, CPI, PPI and retail sales, and from that information they decide whether to increase, decrease or leave on hold the official cash rate.The cash rate is the interest rate that the banks and lenders will pay to the reserve bank. If this increases, your lender will usually pass the cost onto you - the borrower. If the cash rate decreases - the reserve bank intends that the savings should also be passed on by your lender - but this isn't always the case.By moving the interest rates up and down, the RBA tries to keep the Australian economy in check, by either slowing things down to keep the cost of living under control, or speeding up spending to help boost growth in certain areas.What are the different types of interest rates?The two main types of interest rates are Variable and Fixed.Variable rates are usually a bit lower, and you pay the best going rate at the time. If the cash rate increases, your lender will increase your variable interest rate. But if the cash rate decreases, your repayments will usually go down.Fixed interest rates are locked in for a period of time -usually just a couple of years - so that you know exactly how much you will need to budget for. This can be helpful for borrowers on a strict budget who can't afford a lot of interest rate rises in the short term. However you will usually pay a higher interest rate overall if you choose this option.Which interest rate is best for me?The decision of whether to choose a variable or fixed interest rate should be made after carefully considering your own personal needs and commitments. A mortgage broker should be able to help you weigh up the pros and cons to work out the best option. ...
View on Facebook (opens in a new tab)

06

Contact

Disclosure

Credit services provided by Credit Representatives of: Mortgage Australia Group Pty Ltd, Australian Credit Licence 377294

Find Us

We are located in Sydney, servicing any clients around Australia

View the Privacy Policy